What a buyer will pay for your business is decided in the years before you sell it. By the time there’s a buyer at the table, most of the price has already been set.
A great many independent hardware stores, home centers and equipment dealers are run by owners who are thinking about what comes next. Some will sell to an outside buyer or a larger group. Some will pass the business to a son or daughter. Some will sell to the managers who have been running it alongside them for years.
The common thread is that most of them start preparing later than they should. Not because they’re careless, but because running the business takes all the time there is, and the exit always feels a few years further off than it turns out to be.
Buyers pay for what they can verify
An owner knows what the business really earns. They know which department carries the others, which year was unusual and why, and what the place could do with a little more attention. A buyer knows none of that, and won’t pay for it on trust.
What a buyer pays for is what they can see and confirm: earnings that show up consistently in the financials, inventory that holds its value when it’s counted, and an operation that will keep running without the person who built it. Everything that can’t be confirmed tends to be discounted, and uncertainty is usually discounted heavily.
So the gap between what a good business is worth and what it sells for is often not a performance gap at all. It’s a documentation gap, and unlike a performance gap, it can be closed on a schedule.
The question underneath all the others
If you stepped away for a month, what would break first?
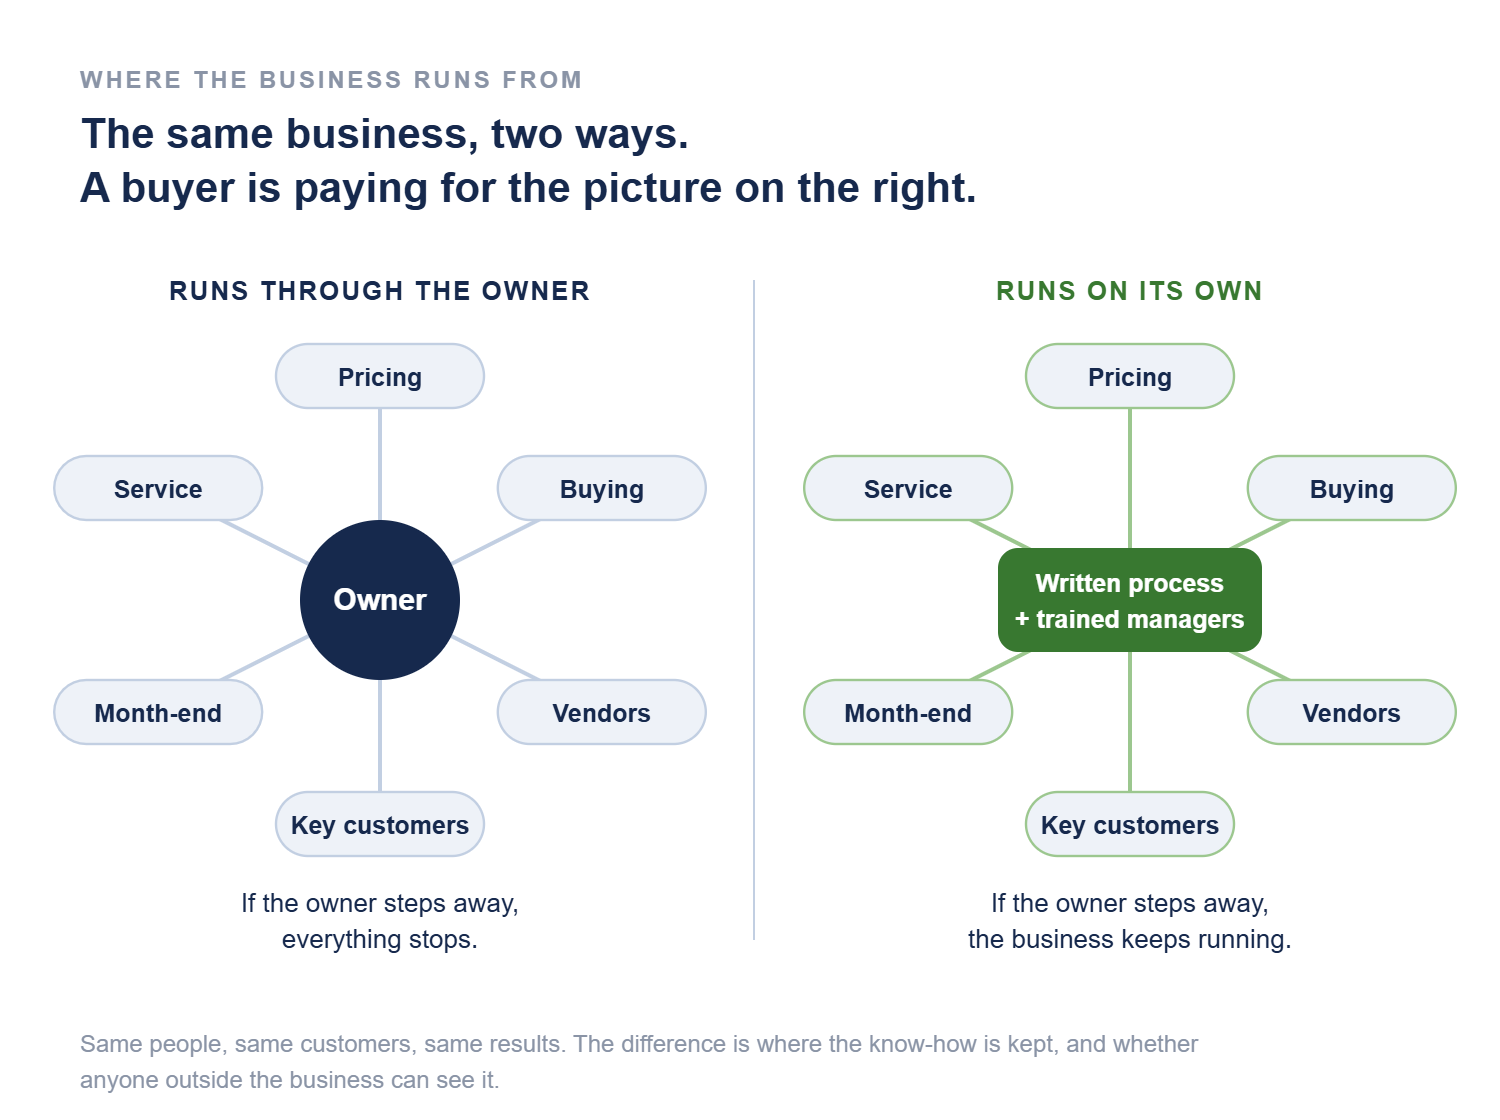
In many independent businesses, the owner is the buyer, the pricing department, the person who knows which vendor will take a return, and the one customers ask for by name. That’s a strength while the owner is there. To a buyer, it’s a risk, because everything the owner does in their head leaves with them.
The dependence usually shows up in three places. Leadership — decisions only the owner makes. Process — work that gets done right only because the owner checks it. Knowledge — the reasoning behind a hundred decisions that has never been written down, because it was always obvious to the person making them.
Reducing that dependence is some of the most valuable preparation there is, and it takes time. Buying needs guidelines someone else can follow. Pricing needs to run on rules rather than memory. Managers need to have made real decisions, with real results, for long enough that a buyer can see the business runs without the owner in the building every day.
Four questions a buyer or successor will ask
Whoever takes the business on, from outside or inside the family, is trying to answer the same few questions. The answers are only worth something if they’re written down.
01
Is the inventory worth what the balance sheet says? Answered by recent physical counts, how far they were off, and a record of how variances were handled.
02
Will I inherit problems I can’t see? Answered by a month-end that can be trusted and a history of issues found and fixed, not hidden.
03
Can the team keep it running without the owner? Answered by trained people, documented procedures and managers with a track record of their own.
04
Can I understand how it performs without a long learning curve? Answered by a year or more of consistent monthly reviews, including margin by department and how service is measured.
Very little of that can be produced in the few months between deciding to sell and sitting down with a buyer. You can’t manufacture a history during due diligence. You can only have already had it.
What it looked like for one owner
An owner approaching retirement needed to understand what he had actually built. The business was good, and everyone who worked there knew it. But almost none of what made it good was written down anywhere a buyer could see.
The work wasn’t a turnaround. It was making the business visible. Processes that had existed only in people’s heads for years were documented. Performance that had always been felt rather than tracked was measured. Decades of how they actually ran the place were put into terms a buyer could check for themselves.
The business sold for significantly more than expected. It was already good. The work was proving it.
Questions to ask yourself now
You don’t need a buyer at the table to see where the gaps are. Answer these honestly and the list of what to work on usually writes itself.
Could someone other than you close the month, and would you trust the result?
When was the last full physical inventory, and how far off was it?
Does pricing follow rules, or does it depend on who is at the counter?
Can you show what the service department earns, not just say it does well?
Is there one customer, one vendor, one line or one employee the business leans on too hard?
If a manager left tomorrow, is how they do their job written down anywhere?
Which decisions still only you make, and does anyone else know why you make them the way you do?
Would your accountant say the inventory figure on the balance sheet is right?
Every “no” or “not sure” on that list is something a buyer will find and price. It’s also something that can be fixed on a schedule, if the schedule starts early enough.
Inventory is where the surprises happen
In a retail or dealer sale, inventory is often the largest single asset changing hands, and it’s commonly counted and valued at or near closing. That’s the moment years of slow stock, inaccurate on-hands and optimistic costing come due all at once.
Aged stock that a buyer will discount or refuse can be returned, transferred, repriced or worked down through a deliberate plan if there are a few years to do it, and much of the cash recovered. At the closing table, the only question left is how large the discount will be.
Accuracy matters just as much. A balance-sheet figure nobody has verified in years is not an asset, it is a claim. If the count at closing comes in well below the books, the buyer doesn’t just pay less for the missing inventory. They start asking what else in the numbers isn’t quite right. The first real physical inventory in a decade isn’t something you want to be doing while a buyer watches.
Passing it to family is still a handover
Succession inside a family or to long-time employees can feel like a different thing entirely. Emotionally, it is. Operationally, nearly all of the same questions apply.
Here the risk is often not a discount. It is that decades of judgment walk out the door with the owner, and the next generation spends years rediscovering things that were already known. They don’t need the keys explained. They need the reasoning behind the decisions.
There’s usually still a price, even when it’s structured gently over years, which means the numbers have to be believable to everyone involved — including siblings who aren’t taking over, and the lender if there is one. And there’s one more question an outside sale doesn’t raise: is the successor ready? That’s best answered by giving them real responsibility early, while the current owner is still there to help.
Two to five years is the window that pays
Nothing is urgent yet, which is exactly why it works. A buyer discounts uncertainty, and the cure for uncertainty is a run of years where the numbers were true, the margins held and the processes were written down before anyone asked.
First
Get numbers you trust: a clean month-end, margin by department, an inventory that has actually been counted.
Then
Move decisions to managers, write down how the business runs, and train the team on it.
Run
Let it run that way long enough to build a record of results without the owner at the center of every decision.
Sale
Go into due diligence with every claim already backed up, so the conversation is about price rather than doubt.
If a deal is already moving, the work becomes defensive: making sure nothing surfaces late, because a surprise found by the other side costs trust, and trust gets priced. There’s less room to improve the business, but considerable room to stop it being discounted.
The legal, tax and deal-structure side belongs with your accountant and attorney, and it deserves good advisors. But they work with the business as it is when they arrive. The operational side — the margins, the inventory, the reporting, the people — decides how much there is for them to work with.
The point is not the sale
None of this is really about selling. It is about building a business that is valuable, transferable and less dependent on any one person. Every piece of it is something the business should have had anyway: pricing that holds without supervision, a month-end that can be trusted, an inventory figure somebody has actually counted, procedures that survive the person who wrote them.
A business that runs without you runs better while you still own it. It just also happens to be worth more when you stop.
That’s the other benefit of starting early. If the exit takes longer than planned, or never happens at all, nothing has been wasted. You’ll have spent those years owning something worth owning.
How this connects
Area: Executive — leadership, succession and exit. The decisions that only get made once.
Applies across: Revenue, Operations and Administration — a buyer looks at all of them, and so should an owner planning to step back.
Read next: Preparing to Sell or Pass On the Business — what the other side will look at, and where to start.
Also useful: You Cannot Sell Your Way to a Better Year — why margin, not volume, is usually the fastest way to raise what the business earns.
ProfitEdge Systems helps independent retailers and dealers improve profitability and operating performance through consulting, training, and intelligence tools. See how we help →
Free checklist
The Physical Inventory Planning Checklist
Two pages. Everything to do six weeks, two weeks and one week out, the count-day rules, and a review sheet that shows the gross variance, not just the net. One email address, nothing else.
Free follow-up kit
The Follow-Up Kit
Four printable pieces: a short huddle playbook for managers, the huddle form, a one-page field job aid, and a guide to turning the reports you already have into working lists. One email address, nothing else.
Free self-check
The Exit-Readiness Self-Check
Two pages. What still runs through you, the four questions a buyer or successor will ask, and a place to name your first three gaps. One email address, nothing else.
Free worksheet
The Shrink Investigation Worksheet
Two pages. A five-step check for every significant variance, an item log, where shortages hide in an equipment and hardware store, and how to spot a pattern before anyone is accused. One email address, nothing else.
Free self-check
The Small-Office Controls Self-Check
Two pages. Who does what on a payment, the five control activities, first fixes for a two-person office, and a login review. One email address, nothing else.
Free counter log
The Missed-Sale Log
Two pages. A counter log for every request you couldn’t fill, a weekly review that gives each signal an owner, and a place to track patterns across the month. One email address, nothing else.
Free account review
The Commercial Account Review
Two pages. A snapshot of your five most important commercial, fleet, municipal or farm accounts: what they run, the terms on file, and what each account really earns. One email address, nothing else.
Free planning sheet
The Before-the-PO Planning Sheet
Two pages. Why you’re buying it, four questions to answer before the cash goes out, the program on one page, and how to run a controlled test when the evidence is thin. One email address, nothing else.
Free template
The Customer Deposit Policy Template
Two pages. Write your deposit terms once, set how deposits are handled at the counter, and reconcile open deposits every month. One email address, nothing else.
Free worksheet
The Revenue Leak Worksheet
Two pages. Check warranty, co-op and programs, labor, vendor terms and floorplan, put a yearly dollar figure on each leak, and rank them against shrink with an owner for every fix. One email address, nothing else.
Free morning review
The Work Order Stage Review
Two pages. A morning sheet for every open job, with its stage, what it’s waiting on, the next step and who owns it, plus a stage-by-stage count of where work stalls. One email address, nothing else.
Free monthly review
Monthly Margin Questions
Two pages. The four questions an owner should be able to answer every month, set out as a sheet to fill in when the statement arrives, with a checklist of where margin drifts. One email address, nothing else.
Free planning sheet
The Decision-First Report Request
Two pages. Before asking for a new report or a new system, write down the decision, who makes it, how often, what counts as an exception and whether the data can be trusted. One email address, nothing else.
Free working sheet
The Month-End Exception Review
Two pages. The five questions worth settling before you build anything, and a daily / weekly / before-the-close sheet with the owner column left blank for your own names. One email address, nothing else.
Shrink Isn’t Only Theft
When the count comes up short, theft is the first thought. Often the stock was never there, or it left without anyone recording it. Sort the cause before you act.
Trust Is Not a Control
Controls are not a judgment about anyone. They are a judgment about whether one person could move money and hide it, and they protect the people you trust most.
Commercial and Fleet Customers Are Different
A down mower is a frustrating weekend for a homeowner. For a landscaper, it is a crew standing still.
Customer Deposits Aren’t Your Money Yet
A deposit is money you are holding, not money you have earned. Book it as a sale and the numbers start telling a story that is not true.
Bring the problem you keep re-solving
Most of what ends up in these articles started as a question from a shop owner or a dealer principal. If something here sounds like your month, say so and we will look at it together.